
Debt relief companies help individuals manage overwhelming unsecured debt by negotiating with creditors to reduce the total amount owed. They focus on debts like credit cards, medical bills, and personal loans, but not secured debts like mortgages or car loans. These companies typically require you to stop payments to creditors and deposit funds into a dedicated account for settlements.
Key points to know:
- Debts handled: Unsecured debts (e.g., credit cards, medical bills).
- Process: Free consultation → Payment halt → Negotiation with creditors → Settlement.
- Costs: 15-25% of settled debt, charged only after successful settlement (per FTC rules).
- Risks: Credit damage, potential lawsuits, and tax liabilities on forgiven amounts.
- Alternatives: Credit counseling, debt consolidation, or bankruptcy.
Debt relief can provide a structured solution for those with severe financial strain, but it’s important to weigh the risks and fees before proceeding.
How Debt Relief Companies Work
The Complete Process
Debt relief typically starts with a free consultation. During this session, the company evaluates your financial situation by reviewing your debts, income, and expenses to determine if you qualify for their services.
If you’re eligible, the company designs a customized plan for you. This plan often involves halting direct payments to creditors and instead directing monthly contributions into a dedicated account. These funds are then used to negotiate settlements with creditors, aiming to reduce the total amount owed. Once a settlement is reached, the company secures a written agreement. Depending on the terms, payment is made either as a lump sum or through structured installments, with any remaining balance forgiven.
The success of this process relies heavily on proper fund management, which is explained further below.
How Savings and Escrow Accounts Work
When a settlement is finalized, the company will seek your approval to release the necessary funds from your dedicated account. These accounts are central to managing payments and ensuring that settlements are handled efficiently.
The time it takes to complete the program depends on various factors, which are outlined below.
How Long Programs Take
The length of a debt relief program can vary significantly. Key factors include the total amount of debt, how quickly you contribute to your account, and the speed at which creditors agree to settle. In most cases, the timeline is closely tied to your financial capacity and monthly payment ability. This flexibility highlights the personalized nature of these programs, as they are designed to match your specific financial situation.
Costs, Fees, and Legal Rules
What Companies Charge
Debt settlement companies typically charge between 15% and 25% of either the original debt amount or the final settled amount. For instance, if you settle a $27,000 debt at 50% with a 15% fee, you’d pay about $4,050 in fees, bringing your total payment to roughly $18,000. These fees can significantly impact your overall savings.
Key legal rule: U.S. law, specifically the FTC Telemarketing Sales Rule, prohibits debt relief companies from charging upfront fees. According to the Federal Trade Commission:
"It’s illegal to charge upfront fees. You can’t collect any fees from a customer before you have settled or otherwise resolved the consumer’s debts."
This means companies can only collect their fees after successfully settling each debt. If multiple debts are negotiated separately, they can charge fees for each settlement – but never in advance.
Legal Protections and Rules
Federal regulations provide additional safeguards for consumers. Rules like the FTC Telemarketing Sales Rule require debt relief companies to clearly disclose their pricing, escrow requirements, and terms before enrollment. Consumers also retain full control over their escrow accounts, including any interest earned, and can withdraw funds at any time without penalty.
The Consumer Financial Protection Bureau advises steering clear of companies that demand fees before settling debts. These protections are in place to ensure transparency and fairness, helping debt relief companies focus on reducing your debt rather than creating additional financial burdens.
Free Debt Review by Steps To Be Debt Free
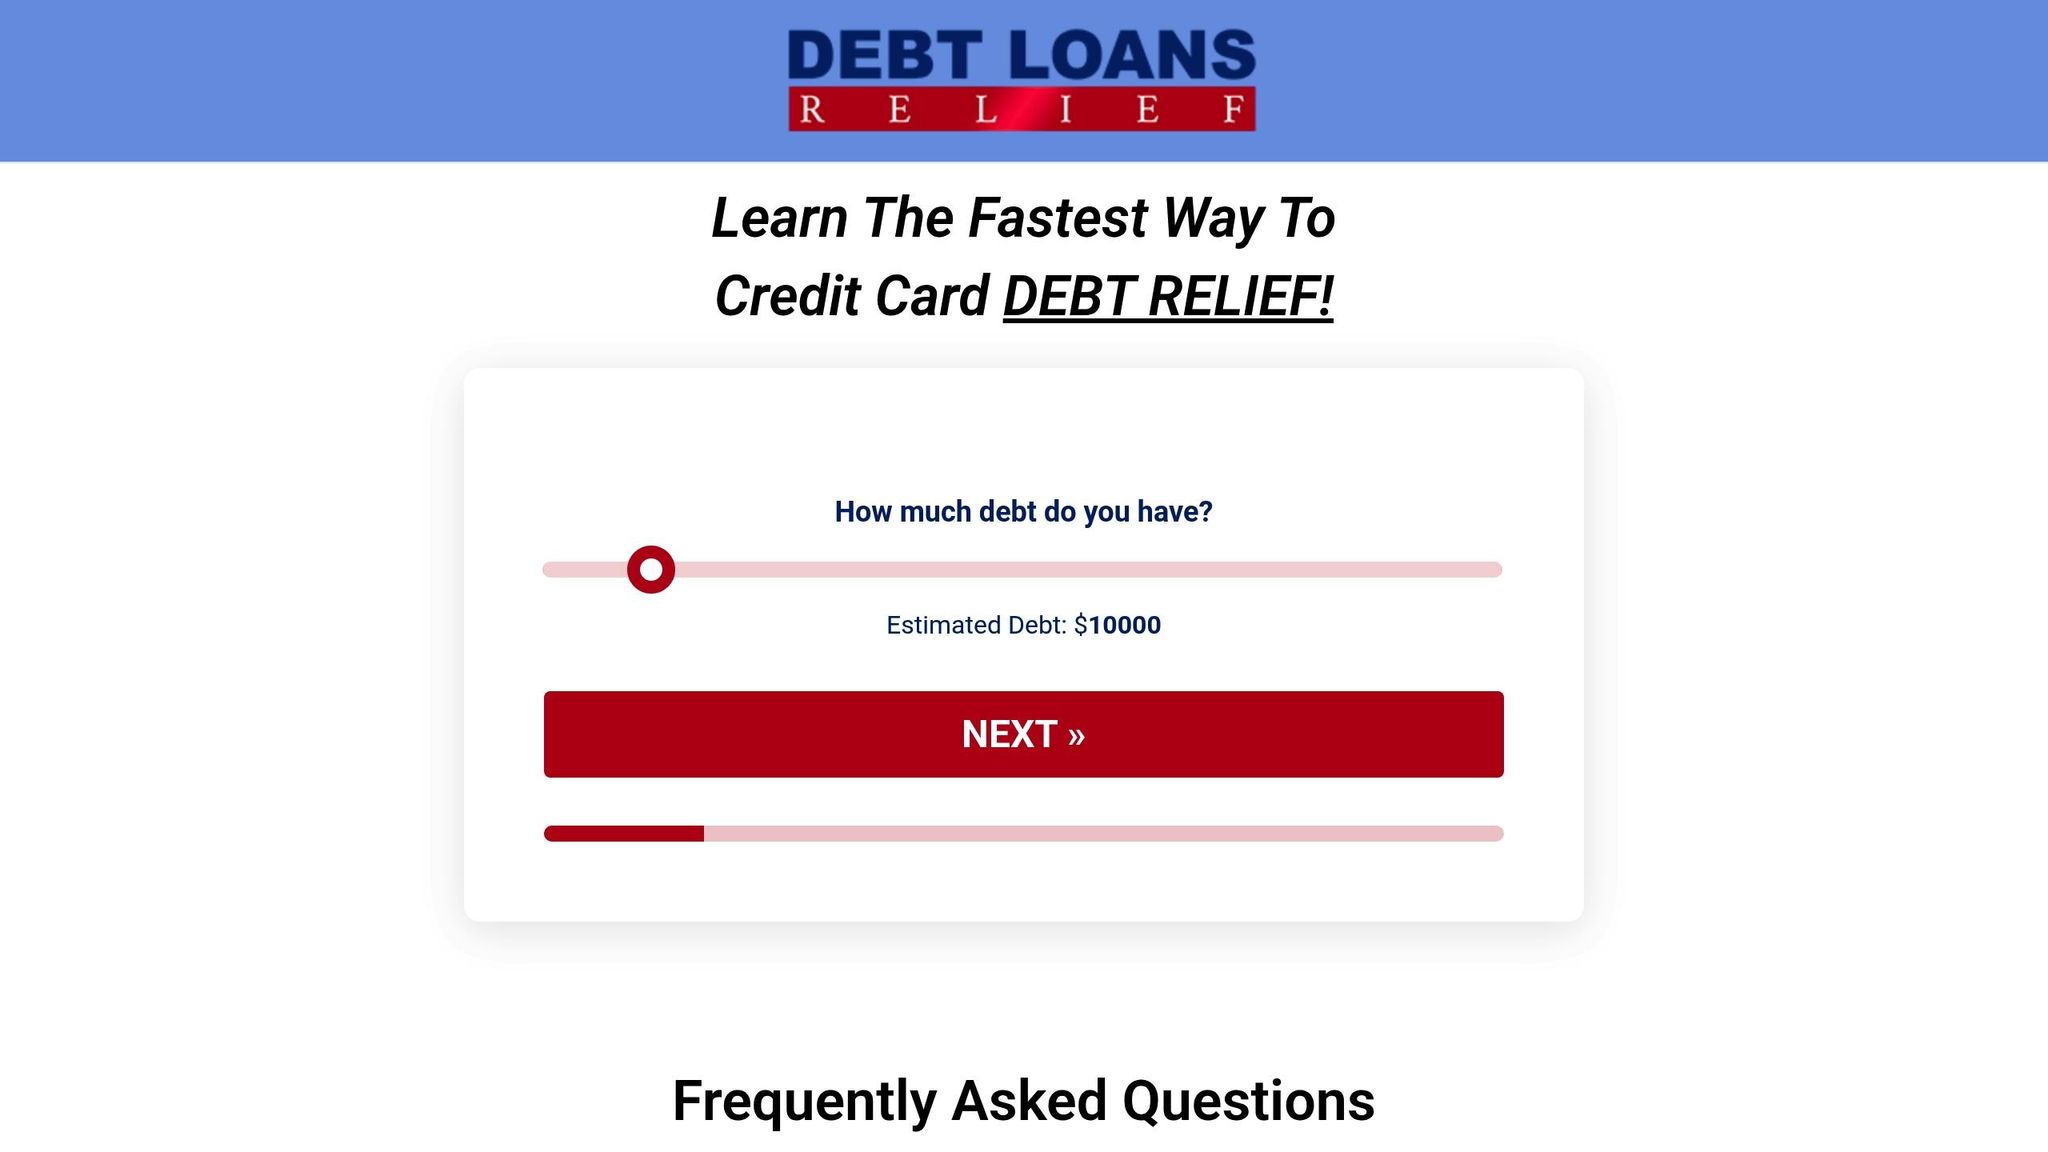
Adding to these protections, Steps To Be Debt Free offers a free debt review. This service provides personalized recommendations based on your financial circumstances, helping you decide if debt relief services are the right choice for you.
Benefits and Risks of Debt Relief Companies
Benefits of Using Debt Relief Companies
Debt relief companies can step in to negotiate with creditors, aiming to lower the amount you owe on high credit card balances. If successful, this could mean paying less than the full debt amount.
Another perk is that they take over all communication with your creditors. This can be a huge relief, sparing you from constant collection calls and letters while negotiations are ongoing. For many, this alone can significantly reduce stress.
These companies also bring a level of expertise that most individuals don’t have. They understand creditor policies, know how to negotiate effectively, and can develop settlement strategies. This specialized knowledge might help them secure better terms than you could on your own. For those overwhelmed by debt, having a single point of contact to manage the process can simplify things.
But while these benefits sound appealing, they come with some serious risks.
Risks and Downsides
Using a debt relief company can backfire if things don’t go as planned. One major risk is that you’ll need to stop making payments to your creditors during the negotiation period. This can lead to late fees, penalty interest, and other charges piling up, which could increase your overall debt.
Your credit score is also at stake. Halting payments can cause significant damage to your credit, making it harder to borrow in the future. On top of that, creditors may ramp up collection efforts, and in some cases, they might even file lawsuits if they’re unwilling to work with the debt relief company.
Another issue to consider is taxes. If part of your debt is forgiven, the IRS may count that forgiven amount as taxable income, leaving you with an unexpected tax bill. Between the company’s fees, added penalties, and potential tax liabilities, some people end up in a worse financial position than when they started.
Pros and Cons Comparison
Here’s a quick look at how the benefits and risks stack up:
| Aspect | Benefits | Risks |
|---|---|---|
| Debt Amount | Can negotiate reductions with creditors | Some debts may remain unsettled, and penalties can offset savings |
| Payment Strategy | Professional management of payments | Stopping payments can result in late fees and penalty interest |
| Creditor Relations | Reduces stress by handling creditor communication | Creditors might refuse to cooperate, leading to lawsuits |
| Credit Impact | Fewer collection calls during negotiations | Can severely harm your credit score, limiting future borrowing options |
| Costs | Potential to lower overall debt | High fees and other costs can add up |
| Final Outcome | Offers a structured debt resolution plan | Risk of ending up deeper in debt after the process |
Before deciding to work with a debt relief company, it’s important to weigh these pros and cons carefully. Consulting a tax advisor or attorney can help you understand how forgiven debt might affect your taxes and overall financial situation.
Key risks commonly associated with debt relief services.
sbb-itb-2a9374f
Debt Relief Program Pros and Cons (2025)
Example: How Steps To Be Debt Free Works
Following our earlier discussion on debt relief costs and legal protections, let’s break down how Steps To Be Debt Free operates to help you tackle your financial challenges.
Personalized Debt Review
Steps To Be Debt Free begins by conducting a detailed evaluation of your financial situation. You’ll need to provide key information, such as your credit card balances, monthly payments, and the current status of those payments. The process is straightforward and guided, ensuring you enter accurate details without confusion.
Tailored Solutions and Expert Guidance
Once your debt review is complete, the platform offers personalized advice based on your unique circumstances. This includes a free consultation with financial experts, who will explain your options and recommend the best strategies for managing your debt. The goal is to make the entire process as clear and actionable as possible, so you can take informed steps toward resolving your financial burdens.
Why It’s Simple to Navigate
Designed specifically for users in the U.S., the platform offers an intuitive interface that works seamlessly on both desktop and mobile devices. Features like autosave ensure that your progress is never lost, allowing you to complete the debt assessment at your own pace. Plus, with no major upfront commitments, you can explore your options and start working toward financial freedom without any long-term obligations holding you back.
Is a Debt Relief Company Right for You?
Choosing whether to work with a debt relief company hinges on your unique financial situation and how severe your debt has become. These services aren’t always essential, and knowing when they’re appropriate can help you avoid unnecessary fees and potential harm to your credit.
You might be a strong candidate for debt relief if you meet a few key conditions. For starters, you should owe at least $7,500 in unsecured debt – anything less may not justify the costs or risks involved. Unsecured debt includes things like credit card balances, personal loans, medical bills, and store cards. However, secured debts like mortgages or car loans are not eligible for settlement. Meeting these basic criteria is just the first step in determining if this option is a fit for you.
Another important factor is your overall financial strain. If you owe more than half of your gross annual income in unsecured debt, debt relief may be worth considering. To put this into perspective, the average person seeking debt settlement typically carries about $27,000 in debt, most of it tied to credit cards.
Life events and financial hardships often push people toward professional debt help. If you’ve recently faced a layoff, a significant pay cut, unexpected medical expenses, or other emergencies that have left your debt feeling unmanageable, a debt relief company might offer a structured way forward. Similarly, if you’re struggling to make even the minimum payments and your credit score is taking a hit, settlement could be a viable route. Certain debt patterns can also signal the need for help. For instance, if you’re stuck in a cycle where your credit card balances never seem to shrink despite regular payments, or if you owe a large sum to a single creditor, debt relief might help you break free. More pressing situations, like lawsuits over unpaid credit card debt or being unable to repay the full amount you owe, often call for immediate professional assistance.
Before committing to debt relief, it’s wise to explore other options. Alternatives like debt consolidation or credit counseling could resolve your issues without the same risks to your credit score.
If you decide to move forward with debt relief, make sure to choose a reputable company. Look for one that doesn’t charge upfront fees and is accredited by organizations like the American Association for Debt Resolution. Keep in mind that debt settlement comes with significant risks – your credit score could take a major hit, creditors might refuse to negotiate, and you could face late fees, penalty interest, lawsuits, or even tax consequences on forgiven debt.
Ultimately, the decision comes down to a clear-eyed assessment of your financial situation. If you’re able to manage your debts through budgeting, increasing your income, or other strategies, debt relief likely isn’t necessary. But if financial hardship has left you with no realistic way to repay what you owe, working with a trustworthy debt relief company could be the step you need to reset your finances. Taking the time to evaluate your position thoroughly will help you determine whether this is the right path for you.
FAQs
Are there tax consequences if a debt relief company helps reduce or forgive my debt?
When a debt relief company manages to reduce or forgive part of your debt, the IRS might treat the forgiven amount as taxable income. For instance, if $10,000 of your debt is wiped out, you could be required to declare that amount as income on your tax return.
That said, there are exceptions to this rule. If you’re insolvent – meaning your total liabilities are greater than your total assets – at the time the debt is forgiven, you might not owe taxes on the forgiven amount. To navigate this and understand your specific circumstances, it’s wise to consult a tax professional.
How can I find out if I’m eligible for debt relief services?
To see if you qualify for debt relief services, most companies focus on two main criteria: having a steady income and carrying at least $7,500 in unsecured debt. This includes things like credit card balances or medical bills.
If managing your debt has become unmanageable and you’re finding it hard to keep up with payments, reaching out to a debt relief company could be a step worth considering. They can evaluate your financial situation and suggest solutions that align with your specific needs.
How can I choose a trustworthy debt relief company?
When choosing a debt relief company, pay close attention to certifications, fees, and realistic promises. Opt for companies accredited by respected organizations like the National Foundation for Credit Counseling (NFCC) or the Financial Counseling Association of America (FCAA). These accreditations show that the company follows established industry standards.
Watch out for the fees – reliable companies usually charge 15% to 25% of the total debt enrolled, but they should never ask for upfront payments. Also, ensure their proposed repayment timeline fits your financial goals. Be wary of companies that promise to wipe out all your debt quickly, as such claims are often too good to be true. By taking these precautions, you can find a trustworthy partner to help manage your debt effectively.
