
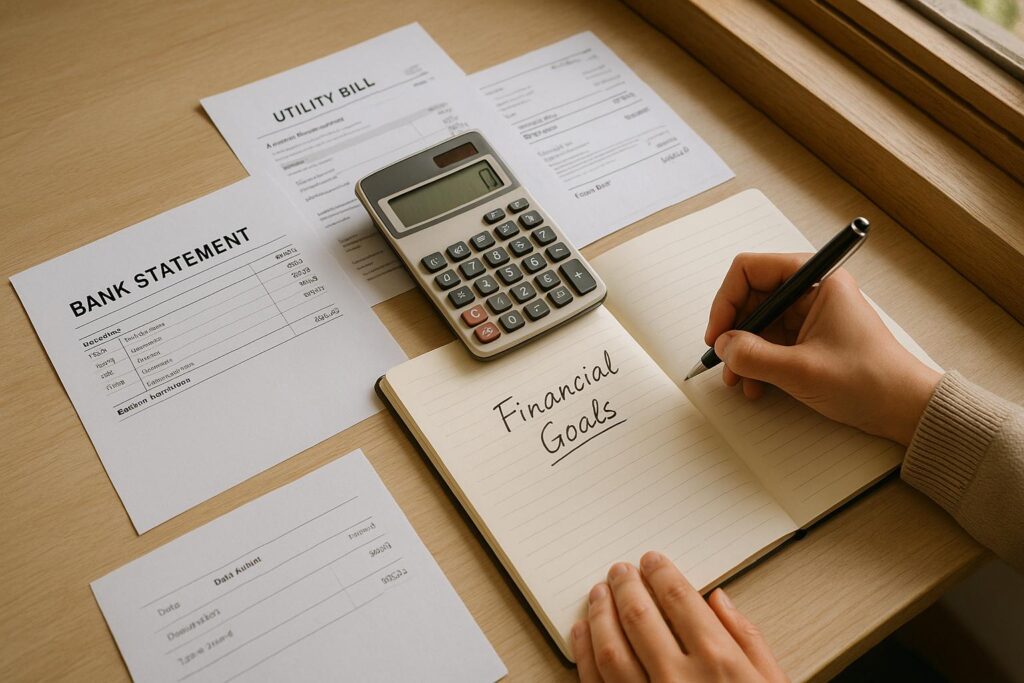
Credit counseling helps you manage debt and improve your financial health. Preparation is key to making the most of your session. Here’s what you need to do:
- Gather financial documents: Include pay stubs, tax returns, credit card statements, loan documents, utility bills, and bank statements.
- Organize your paperwork: Use folders for categories like income, debts, expenses, and assets. Create a one-page summary of key figures.
- Review your finances: Track income, expenses, and calculate your debt-to-income ratio. Identify problem debts and prioritize them.
- Check your credit report: Get free reports from Experian, Equifax, and TransUnion. Look for errors, credit utilization, and negative marks.
- Set clear financial goals: Use the SMART framework to define short-term, mid-term, and long-term objectives. Prioritize urgent issues.
- Prepare questions: Ask about budgeting, debt consolidation, repayment plans, and available resources.
How Should I Prepare For A Credit Counseling Session In Fresno? – Crazy About Credit Cards
Gather Your Financial Documents
When preparing for a credit counseling session, having all your financial documents in order is crucial. Your counselor needs a clear and complete view of your finances to develop a plan that works for you. Missing paperwork can slow down the process, so being thorough from the start saves time and ensures you get the most out of your session.
Documents You Need
Start by collecting income-related documents. This includes your most recent pay stubs (typically from the last 2–3 months), last year’s tax returns, and any records of additional income, like rental payments, child support, or freelance earnings. Don’t forget to include statements for Social Security benefits or disability payments if you receive them.
Next, gather debt-related documents. Credit card statements are key – make sure they show current balances, minimum payment amounts, interest rates, and due dates. Even if a card has a zero balance, include it to give your counselor a complete picture. You’ll also need loan documents for any mortgages, car loans, student loans, and personal loans. Be sure to include medical bills, collection notices, and any other outstanding debts.
You’ll also need monthly expense records. Bring utility bills, insurance premium statements, and bank statements from the past three months. If you have receipts or records for recurring expenses like groceries, transportation, or childcare, include those as well.
"Being well-prepared ensures you get the most out of your credit counseling session. Gather all relevant financial information, such as recent bills, statements, and income details, to provide a clear picture of your financial standing." – GreenPath Financial Wellness
Finally, prepare asset information. This includes bank account and investment account statements, property deeds or mortgage documents, and vehicle titles or loan papers. Even if your assets are minimal, having this information helps your counselor get a full understanding of your financial situation.
How to Organize Your Documents
To keep everything in order, use clearly labeled folders or envelopes. For example, you can create separate folders for "Income", "Debts", "Monthly Expenses", and "Assets." Arrange the documents in each folder chronologically, with the most recent ones on top.
Consider creating a one-page summary with key figures like your monthly take-home pay, total debt balances, minimum monthly payments, and estimated expenses. This quick reference sheet can save time during your session and help you provide information without digging through piles of paperwork.
If your session will be virtual, scan or photograph your documents and store them in password-protected folders on your computer or smartphone. Make sure the scans are clear, with all text and numbers legible, especially account details and balances.
Whether you’re using physical or digital copies, keep your documents in a secure but accessible place. A dedicated binder or folder works well for printed materials, while cloud storage with strong password protection is ideal for digital files. Having everything in one place will make your session smoother and more efficient.
Being organized and prepared allows your counselor to fully understand your financial situation and create a plan tailored to your needs. With everything in order, you’ll be setting yourself up for a productive and effective session.
Review Your Financial Situation
Once your documents are neatly organized, it’s time to take a clear-eyed look at your financial situation. This step helps you fully understand your financial standing before meeting with a credit counselor. The more familiar you are with your finances, the better prepared you’ll be to discuss options and make informed decisions. Start by gathering key figures to create a complete financial snapshot.
Track Your Income and Expenses
Begin by calculating your total monthly net income. This includes everything you earn – your main job, side hustles, rental income, child support, or government benefits. Focus on your net income (what’s left after taxes and deductions) since that’s the money you actually have available.
Next, track your expenses over two or three months to get a full picture. Divide them into two categories: fixed expenses (like rent, car payments, and insurance) and variable expenses (such as groceries, gas, and dining out). Don’t forget irregular costs – estimate their monthly average to include them in your budget.
To keep track of cash spending, consider using a budgeting app or saving receipts for accuracy.
Once you’ve got your income and expenses mapped out, calculate your debt-to-income ratio (DTI). Divide your total monthly debt payments by your gross monthly income, then multiply by 100. For example, if you pay $1,200 monthly toward debt and your gross income is $4,000, your DTI is 30%. Financial experts generally suggest keeping this ratio under 36%, with no more than 28% allocated to housing costs.
With this financial snapshot in hand, the next step is diving into your credit report to understand your credit standing.
Check Your Credit Report
Before meeting with a counselor, get free copies of your credit reports from the three major credit bureaus – Experian, Equifax, and TransUnion. You’re entitled to one free report from each bureau annually, which you can access through AnnualCreditReport.com, the only government-authorized site for free credit reports.
Carefully review each report for errors. Look for accounts you don’t recognize, incorrect balances, or outdated information. Mistakes on credit reports are more common than you might think, and correcting them can improve your credit score.
Pay close attention to your credit utilization ratio on each credit card and overall. This ratio shows how much of your available credit you’re using. For instance, if you have a $5,000 credit limit and a $2,000 balance, your utilization ratio is 40%. Keeping this ratio below 30% is generally recommended to maintain a healthier credit score.
Note any negative marks on your report, such as late payments, accounts in collections, charge-offs, or bankruptcies. These items can stay on your report for years – most negative marks remain for seven years, while bankruptcies can linger for up to 10 years. Knowing what’s impacting your credit can help your counselor develop a practical plan.
Also, review the age of your accounts and the length of your credit history. Older accounts typically boost your credit score, so think twice before closing old credit cards, even if they’re not actively used.
Find Your Problem Debts
After reviewing your credit report, identify the debts that put the most pressure on your budget. List all your debts, including their current balances, minimum monthly payments, interest rates, and due dates.
High-interest debts, like credit cards or payday loans, can quickly grow if left unchecked. These should be prioritized, along with any past-due or collection accounts.
Also, pay attention to secured debts – mortgages or car loans, for example – where missing payments could lead to losing your home or vehicle. Even with lower interest rates, these debts are high priority because of the potential consequences of falling behind.
Consider the minimum payment burden of each debt. Even low-interest debts can strain your budget if the payments are too high. In some cases, consolidating multiple debts into one payment may provide some financial relief, even if the interest rate isn’t significantly lower.
Don’t overlook tax debts and student loans, as these can be challenging to discharge through bankruptcy. The IRS offers payment plans and hardship programs, while student loans often come with income-driven repayment options or forgiveness programs.
To simplify things, create a chart that outlines each debt’s balance, interest rate, minimum payment, and current status. Having this visual overview makes it easier for you and your counselor to identify which debts need immediate attention and which ones are manageable under your current budget.
Set Clear Financial Goals
Setting clear financial goals is key to making the most of your credit counseling session. After reviewing your financial situation in detail, these goals act as a roadmap for your next steps. As economist Lawrence J. Peter wisely noted, "If you don’t know where you are going, you will probably end up somewhere else".
"Non-profit counselors look at the whole picture, which is why our results are much better for consumers than other debt resolution options. We look at the consumer’s credit report and budget and then build an action plan that incorporates the consumer’s income, expenses and goals." – Martin Lynch, FCAA President and Director of Cambridge Credit Counseling
Your goals shape the advice your counselor provides. Without them, you risk receiving advice that’s too broad to address your specific needs.
Define Your Priorities
Use your organized financial documents and overview to craft meaningful goals. Make sure your goals follow the SMART framework – Specific, Measurable, Achievable, Relevant, and Timely. Break them down into time-based categories:
- Short-term goals: Focus on manageable tasks, like paying off a single credit card or starting a modest emergency fund.
- Mid-term goals: Work on reducing multiple credit card balances or boosting your credit score.
- Long-term goals: Plan for milestones like saving for retirement or paying off your mortgage.
Tackle goals that address your most urgent financial issues first. For instance, if high-interest credit card debt is eating into your budget, prioritizing repayment should be at the top of your list.
Other common goals include improving your credit score, reducing overall debt, sticking to a practical budget, managing credit use wisely, and easing financial stress.
Prepare Questions for Your Counselor
Once your goals are set, prepare specific questions to ensure the advice you receive aligns with your priorities. Write down questions about budgeting methods, debt consolidation options, repayment timelines, and available support resources.
If you’re dealing with student loans, ask about refinancing or consolidation strategies. With the average college graduate spending about 20 years repaying student loans, expert advice can make a significant difference.
It’s also helpful to inquire about realistic timelines – how long it might take to achieve your goals and what progress markers to aim for. Ask about follow-up support, like access to additional resources or periodic check-ins, to help you stay on track as your financial circumstances evolve.
sbb-itb-2a9374f
Choose a Qualified Credit Counseling Agency
Picking the right credit counseling agency can be a game-changer in your journey toward financial stability. With your goals in mind and questions ready, it’s time to identify an agency that offers genuine support rather than empty promises. A trustworthy agency complements your financial strategy and helps you stay on track with the preparations you’ve already made.
The credit counseling industry includes both reliable non-profits and less reputable entities that prey on vulnerable individuals. While legitimate agencies prioritize education and long-term solutions, questionable ones often push costly debt management plans or promise unrealistic quick fixes. This step is about ensuring you partner with an agency that genuinely supports your path to debt relief.
Check Agency Credentials
Start by confirming that any agency you’re considering is accredited by either the National Foundation for Credit Counseling (NFCC) or the Financial Counseling Association of America (FCAA). These two organizations set the gold standard for credit counseling in the United States.
NFCC-accredited agencies employ counselors who undergo rigorous training and continuing education. Similarly, FCAA members follow strict ethical guidelines and operational standards, ensuring they provide reliable services.
Look for agencies staffed with certified credit counselors, particularly those certified by organizations like the National Association of Certified Credit Counselors (NACCC). These professionals are trained in areas such as budgeting, debt management, and consumer credit laws.
You can verify an agency’s credentials by checking their website for accreditation badges or visiting the NFCC and FCAA directories of approved agencies. If an agency can’t provide clear proof of accreditation or avoids discussing their credentials, it’s a major warning sign.
Understand the Fee Structure
Reputable credit counseling agencies typically offer free initial consultations. This first session, which usually lasts 60 to 90 minutes, should provide a detailed review of your financial situation and preliminary recommendations – without pressuring you to commit.
For ongoing services, most legitimate agencies charge modest fees. Debt management plans, for example, often cost between $25 and $50 per month, with setup fees ranging from $30 to $75. Some agencies even offer sliding scale fees based on your income, and many waive fees for those facing severe financial hardship.
Be cautious of agencies that demand large upfront fees or push you to sign contracts immediately. Reputable counselors give you time to consider their recommendations and avoid high-pressure tactics.
Before committing, ask about all potential costs. Are there fees for educational materials, follow-up sessions, or early termination of programs? A trustworthy agency will clearly explain their pricing structure, including what each fee covers and how long their services last.
Watch out for red flags, such as agencies that guarantee specific results, claim they can erase accurate negative credit information, or promise to settle your debts for mere pennies. These claims are not only unrealistic but often indicate fraudulent practices.
Steps To Be Debt Free
Preparing to tackle your debt can feel overwhelming, but having the right tools and resources can make a big difference. Along with gathering your financial documents and working with a qualified credit counseling agency, using an online platform like Steps To Be Debt Free can streamline the process and help you take control of your finances.
This platform simplifies credit card debt relief by creating a personalized strategy tailored to your specific situation. It collects key details about your debts, payments, and overall financial picture – important information to have on hand for your counseling session. By completing Steps To Be Debt Free’s detailed assessment form, you’ll gain a clearer understanding of your current debt levels, payment statuses, and financial organization. This preparation ensures your counseling session is more productive and focused on solutions.
One of the standout features of the platform is its free debt review consultation. This initial review acts as a valuable starting point before your formal credit counseling appointment. It helps you spot potential problem areas in your finances and equips you with informed questions to ask during your session. With this insight, you can make the most of your time with your counselor and dive straight into actionable strategies.
Conclusion
Being well-prepared makes credit counseling a smoother and more productive experience. Careful preparation lays the groundwork for meaningful financial progress. By organizing your paperwork, understanding your financial standing, and outlining your goals ahead of time, you set yourself up for success.
Your level of preparation has a direct impact on the effectiveness of your counseling session. Arriving with well-organized documents and clear questions allows your counselor to focus on creating tailored strategies instead of spending time piecing together basic details.
Credit counseling is just the first step toward achieving financial stability. The advice and debt management plan you receive will only work if you’re committed to following through. Starting off with your financial information in order makes it far easier to stick to the plan and see results.
Key Takeaways
Effective credit counseling begins with proper preparation. Focus on three essential steps to make the most of your session:
- Gather your financial documents: Collect bank statements, credit reports, bills, and loan details. Having everything ready ensures your counselor has a clear and accurate understanding of your financial situation.
- Evaluate your financial health: Take a close look at your income versus expenses, identify which debts are the most burdensome, and track where your money goes each month. This honest assessment will help you have more productive discussions and find realistic solutions.
- Set clear financial goals: Whether you aim to pay off credit card debt in two years, boost your credit score, or create a manageable monthly budget, defining specific objectives helps your counselor design strategies that align with your priorities.
The better prepared you are for your counseling session, the more likely you are to achieve long-term financial stability.
FAQs
What mistakes should I avoid when getting ready for a credit counseling session?
To get the most out of your credit counseling session, steer clear of these common missteps:
- Showing up unprepared: Bring all the necessary paperwork, like recent bank statements, credit card bills, loan details, and a breakdown of your monthly expenses. Having these on hand will save time and make the session more productive.
- Skipping a financial review beforehand: Take a moment to assess your own finances. Know your income, expenses, and debts so you can share accurate details with your counselor.
- Expecting instant results: Credit counseling is a process. While it’s an important step toward better financial health, it’s not a quick fix. Stay patient and committed to the journey.
By sidestepping these mistakes, you’ll be in a stronger position to collaborate with your counselor and develop a solid plan to tackle your debt.
How do I choose a trustworthy credit counseling agency?
To choose a reliable credit counseling agency, first check if it operates as a nonprofit organization, as many well-regarded agencies do. Verify its accreditation with respected groups like the National Foundation for Credit Counseling (NFCC) or the Financial Counseling Association of America (FCAA). You can also contact your state’s Attorney General or consumer protection office to confirm the agency is properly registered.
A trustworthy agency will clearly outline its services, offer free educational resources, and have positive feedback from reputable sources. Be cautious of agencies that push you into decisions or demand high upfront fees. Following these steps can help you make an informed decision.
What should I ask my credit counselor to get the best results from my session?
To get the most out of your credit counseling session, it’s important to come prepared with questions. These can help you better understand the process and confirm that the counselor aligns with your needs. Here are a few essential ones to consider:
- What services do you offer, and are you accredited or certified?
This helps you confirm the counselor’s credentials and the range of assistance they provide. - What are your fees? Are there any free resources I can access?
Understanding costs upfront ensures there are no surprises and allows you to explore any free tools or advice they might offer. - Will this process impact my credit score?
It’s crucial to know how their recommendations or plans might affect your credit in the short and long term. - How do you develop a debt management plan, and will it suit my financial situation?
This question ensures the plan they propose is realistic and tailored to your unique circumstances.
Preparing these questions in advance can make the session more productive and help you walk away with a clearer path toward your financial goals.
